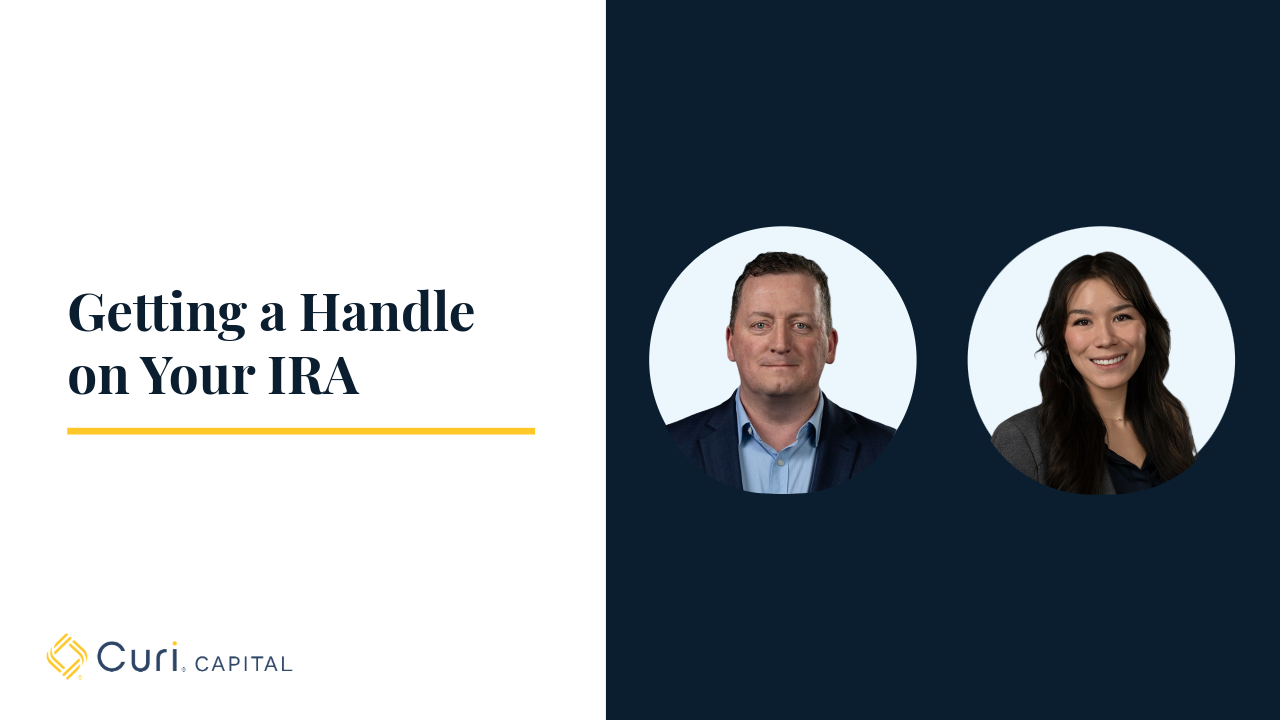
What should you know before taking distributions from your IRA or passing it on to the next generation? In this webinar, Wealth Strategist Jason Largey, J.D. and Wealth Advisor Virginia Cooke, CDFA®, CFP®, break down key IRA considerations, including required minimum distributions (RMDs), qualified charitable distributions (QCDs), inherited IRAs, and naming trusts as beneficiaries, along with common mistakes to avoid and strategies to support your retirement income and long-term estate planning goals.
Key Takeaways
– Understanding Required Minimum Distributions (RMDs): Individuals must begin taking RMDs from most tax-deferred retirement accounts at age 73 or 75, depending on their birth year. Roth IRAs are exempt from lifetime RMD requirements.
– RMD Planning Can Help Avoid Unnecessary Penalties: RMDs are calculated using the prior year-end account balance and an IRS age-based factor. Missing a required distribution can result in a penalty, making it important to understand deadlines and withdrawal requirements.
– Qualified Charitable Distributions Offer Tax Advantages: Individuals age 70½ or older can transfer funds directly from an IRA to eligible charities through QCDs, potentially reducing taxable income while supporting charitable causes.
– Roth Conversions Can Reduce Future RMD Obligations: Converting pre-tax retirement assets into a Roth IRA requires paying taxes on the converted amount but can reduce future RMDs and allow for tax-free growth. The years between retirement and the start of RMDs may present planning opportunities.
– Inherited IRAs Require Careful Tax Planning: Most non-spouse beneficiaries are subject to the 10-year distribution rule, requiring inherited accounts to be depleted within 10 years. Strategically timing withdrawals can help beneficiaries manage the associated tax burden.
– Estate Planning Should Include Regular Beneficiary Reviews: Retirement account beneficiary designations generally operate independently of wills and estate plans. Reviewing designations, updating estate documents every three to five years, and communicating intentions with family members can help support an efficient wealth transfer.
Jump to a topic
01:45 – Understanding Required Minimum Distributions (RMDs)
07:21 – Qualified Charitable Distributions (QCDs)
10:31 – Roth Conversions and Future RMD Planning
11:47 – Understanding Inherited IRAs
17:16 – Naming a Trust as an IRA Beneficiary