Tax-Efficient Wealth Transfer: How Irrevocable Trusts and Other Strategies Can Help Families Preserve Legacy Wealth
Key Takeaways
- If the goal is to remove assets from your taxable estate, the vehicle must be irrevocable. Revocable trusts don’t move the needle on estate tax.
- Three broad categories cover most situations: grantor retained annuity trusts (GRATs), irrevocable life insurance trusts (ILITs), and charitable trusts (CRTs and CLTs).
- Estate planning involves two tax problems, not one: the estate tax at death and the income tax consequences your heirs will face on what they receive.
- The most common planning mistake is making these decisions in isolation rather than with a unified view of the plan.
One of my clients inherited a substantial IRA from her parents and assumed it would simply become part of her family’s financial foundation. Instead, she learned that every dollar withdrawn would be taxed as ordinary income, and the SECURE Act’s 10-year distribution rule meant she couldn’t defer those taxes indefinitely.¹ Her parents had intended to pass on wealth, but without coordinated transfer planning, she was pushed into the top tax bracket, and a meaningful portion of that legacy was ultimately redirected to the IRS.
Passing wealth to the next generation involves more than deciding who receives what; it also requires planning around how the transfer happens, so it doesn’t leave money on the table or create a tax problem for the people you’re trying to help.
The Right Tool for the Job: Irrevocable Trusts
If the goal is to remove assets from your taxable estate, the vehicle must be irrevocable. Revocable trusts are a valuable planning tool, but they don’t move the needle on estate tax. Assets held in a revocable trust are still considered yours for tax purposes, but irrevocable structures are different. Once funded, those assets are legally outside your estate, and any future growth happens beyond the reach of estate taxes. The right structure depends on your goals, assets, and family circumstances, but three broad categories cover most situations: grantor retained annuity trusts (GRATs), irrevocable life insurance trusts (ILITs), and charitable trusts (CRTs and CLTs).
These categories aren’t interchangeable. A GRAT works best when interest rates are low and asset values are depressed, an ILIT makes sense when life insurance is part of the estate picture, and a charitable trust fits when giving is already part of the plan. The right choice is best made with your full financial picture in view.
Two Tax Problems, Not One
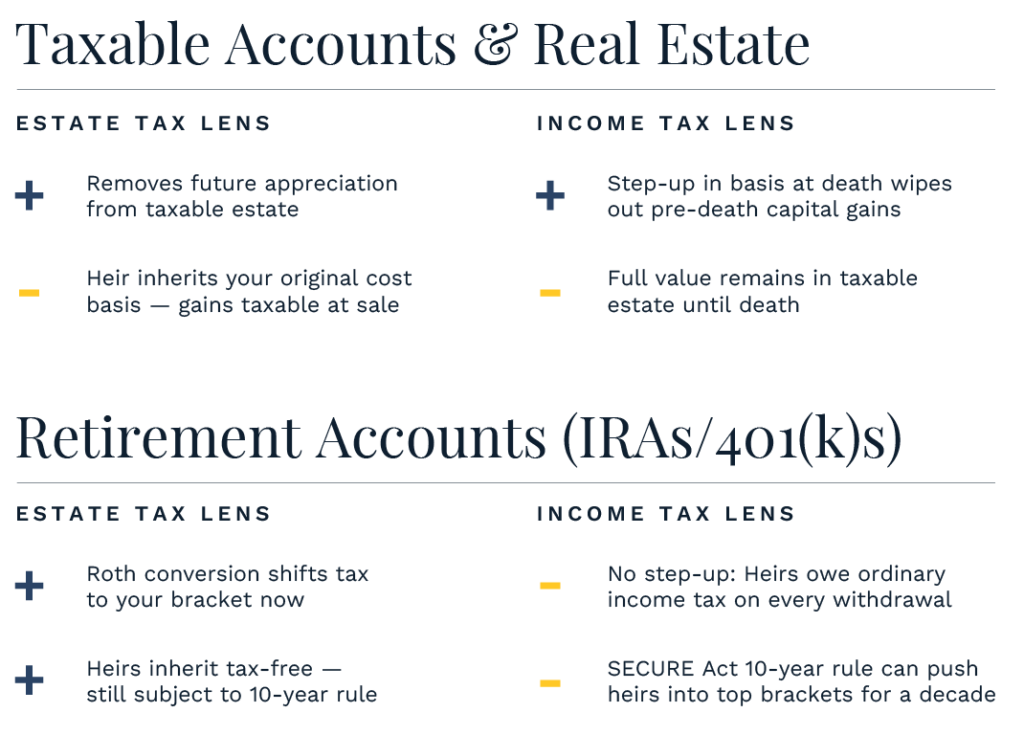
Most estate planning focuses on the estate tax question: How do I keep assets from being taxed at death? But a second tax problem often goes unaddressed until it’s too late: the income tax consequences your heirs will face on what they receive. These two problems call for different, and not always aligned, strategies.
The interaction between these two tax systems is where the most consequential decisions live. A Roth conversion, for example, reduces your heirs’ future income tax burden, but it means paying tax now at your current bracket. Whether that trade is worth making depends on your income, your heirs’ expected income, and the size of the accounts involved.
Coordination Is Key
The most common planning mistake isn’t choosing the wrong trust or missing a gifting deadline. It’s making these decisions in isolation. Funding an irrevocable trust affects your liquidity, a Roth conversion changes your taxable income for the year, and a charitable gift’s timing affects your income tax deduction. Made without a unified view of the plan, these decisions can compound into significant unintended consequences. More intentional coordination ahead of time could have made her parents’ legacy even more impactful and tax-efficient.
Frequently Asked Questions
Does a revocable trust reduce estate taxes?
No. Revocable trusts are a valuable planning tool, but they don’t move the needle on estate tax. Assets held in a revocable trust are still considered yours for tax purposes. If the goal is to remove assets from your taxable estate, the vehicle must be irrevocable. Once funded, those assets are legally outside your estate, and any future growth happens beyond the reach of estate taxes.
What types of irrevocable trusts are used in estate planning?
Three broad categories cover most situations: grantor retained annuity trusts (GRATs), irrevocable life insurance trusts (ILITs), and charitable trusts (CRTs and CLTs). A GRAT works best when interest rates are low and asset values are depressed, an ILIT makes sense when life insurance is part of the estate picture, and a charitable trust fits when giving is already part of the plan.
How are inherited IRAs taxed?
Every dollar withdrawn from an inherited traditional IRA is taxed as ordinary income, and the SECURE Act’s 10-year distribution rule means heirs can’t defer those taxes indefinitely. Without coordinated transfer planning, that can push heirs into the top tax bracket.
How does a Roth conversion affect estate planning?
A Roth conversion reduces your heirs’ future income tax burden, but it means paying tax now at your current bracket. Whether that trade is worth making depends on your income, your heirs’ expected income, and the size of the accounts involved.
Citations
1 Internal Revenue Service. “Retirement Topics — Beneficiary.” IRS.gov.
Disclaimers
The opinions and analyses expressed in this presentation are based on Curi Capital LLC’s (“Curi Capital”) research and professional experience and are expressed as of the date of this presentation. Certain information expressed represents an assessment at a specific point in time and is not intended to be a forecast or guarantee of future performance, nor is it intended to speak to any future time periods. Curi Capital makes no warranty or representation, express or implied, nor does Curi Capital accept any liability, with respect to the information and data set forth herein, and Curi Capital specifically disclaims any duty to update any of the information and data contained in this presentation. The information and data in this presentation does not constitute legal, tax, accounting, investment, or other professional advice.
The content contained herein was generated by Curi Capital with the assistance of an AI-based system to augment the effort.
Certified Financial Planner Board of Standards, Inc. owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER™ and federally registered CFP (with flame design) in the U.S., which it awards to individuals who successfully complete CFP Board’s initial and ongoing certification requirements. CFA® and Chartered Financial Analyst® are registered trademarks owned by CFA Institute.