Summary
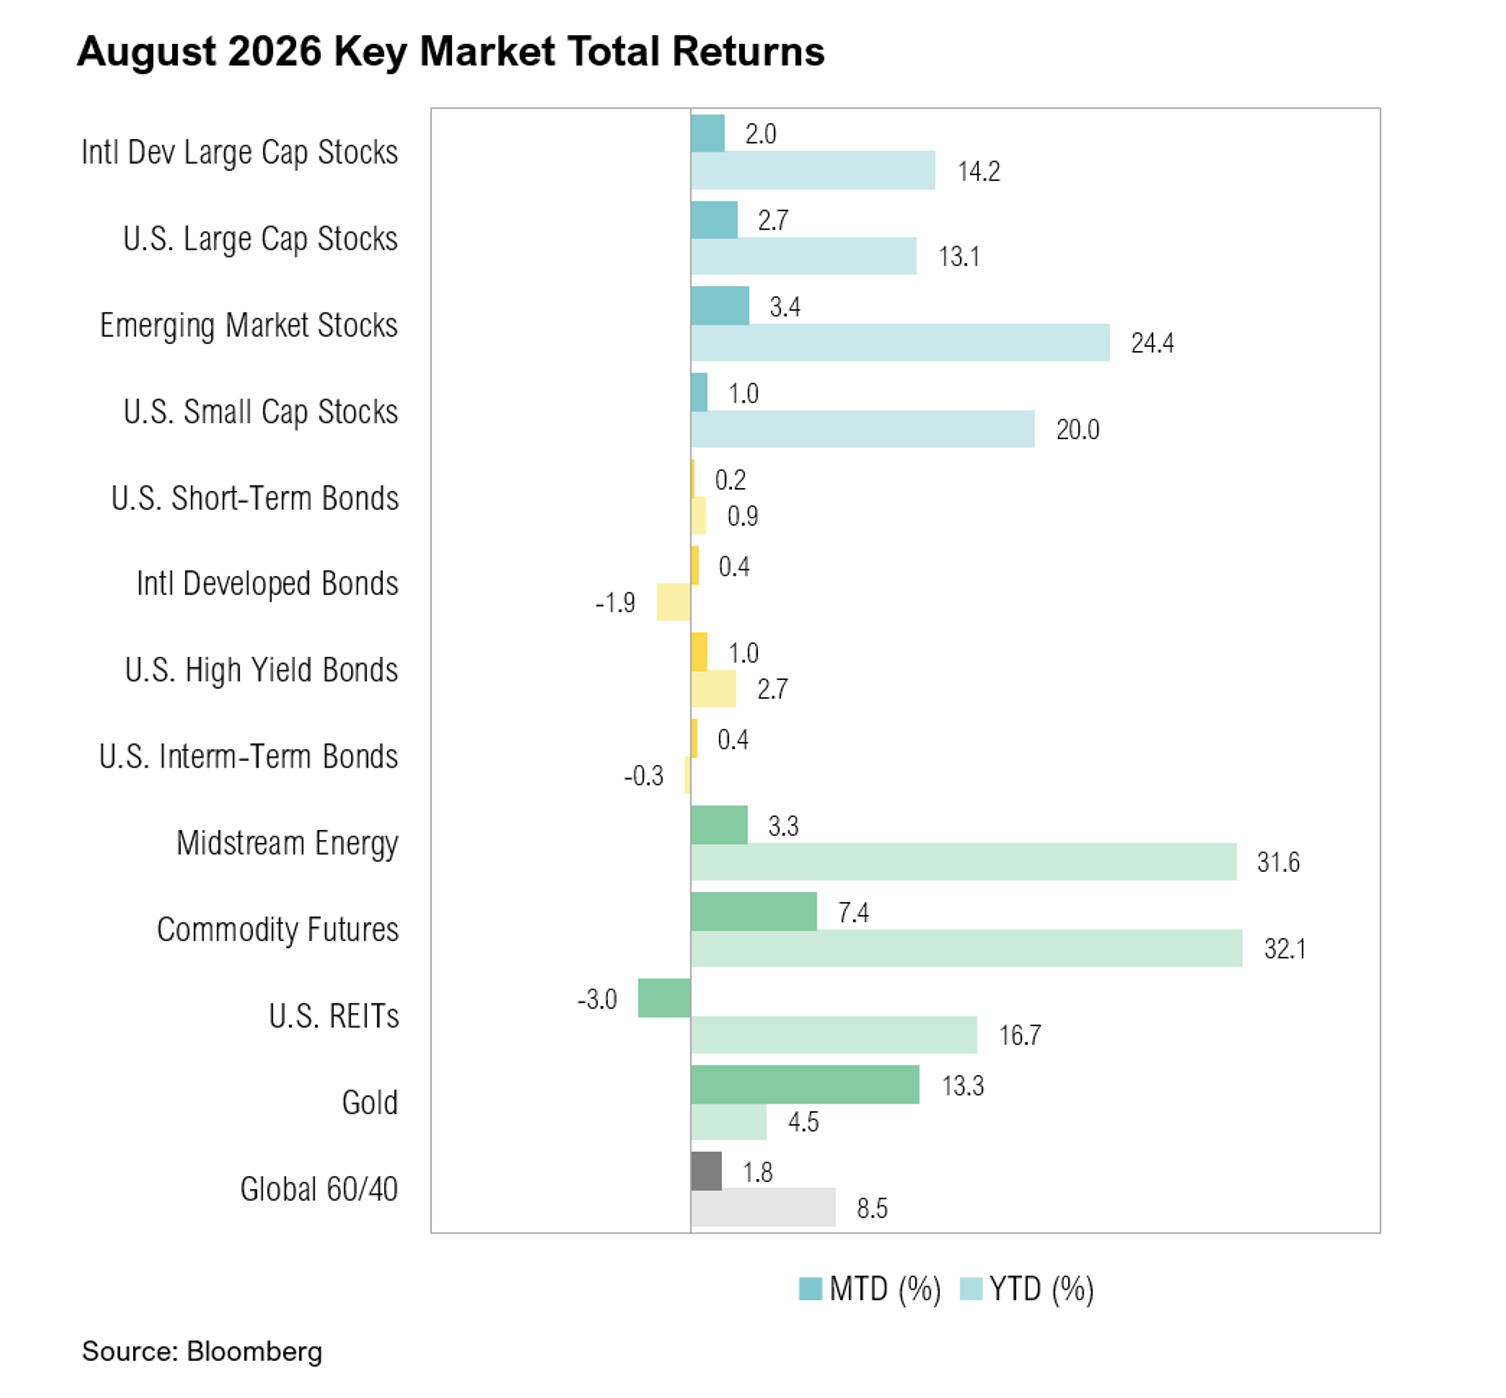
- U.S. large-cap stocks, as proxied by the S&P 500 Index, gained 2.7%, while U.S. small-cap stocks gained 1.0% over the month. U.S. intermediate-term bonds ended the month up 0.4%.
- With more than 97% of S&P 500 companies reporting, second-quarter earnings growth has reached 52%, the strongest since 2021, and profit margins are on track to hit a record 17%.
- NVIDIA announced that quarterly revenue hit a record $96 billion, up 106% year-over-year, and management projected 70% revenue growth over the next fiscal year.
- Federal Reserve Chair Kevin Warsh used the economic symposium in Jackson Hole to reaffirm his opposition to forward guidance and quantitative easing, and he described the economy as fundamentally healthy while acknowledging inflation remains above target.
- The path for longer-term rates remains unusually uncertain, reinforcing our preference for assets with attractive risk/reward potential across a broad range of outcomes, and we generally favor an allocation geared toward higher nominal growth.
Overview
U.S. large-cap stocks, as measured by the S&P 500 Index, gained 2.7% in August, while the small-cap Russell 2000 Index gained 1.0%. Through the first eight months of 2026, the S&P 500 is up 13.1%, and the Russell 2000 is up 20.0%. U.S. intermediate-term bonds, proxied by the Bloomberg U.S. Aggregate Bond Index, increased 0.4% in August, bringing their year-to-date return to -0.3%.
The most recent inflation data came in largely as expected. Core PCE, which excludes food and energy, remained steady at 3.3% year over year, and headline PCE posted a 3.7% year-over-year move. Personal income and spending both beat estimates in July, and second-quarter GDP grew at a 1.5% annualized rate.1 The labor market sent mixed signals as nonfarm payrolls unexpectedly fell by 23,000 in July against expectations for an 80,000 gain. In the past year, labor market gains have averaged just 26,000 a month, including five months with a decline.2 The unemployment rate ticked down to 4.1%, and weekly initial jobless claims remained subdued.
Higher interest rates continue to weigh most clearly on housing. Starts dropped 12.4% in July, and single-family starts fell to their weakest pace since late 2022.3 Consumer confidence also softened. The Conference Board’s Consumer Confidence Index fell to a seven-month low of 89.4 in August.4 Manufacturing and services PMIs were consistent with growth. The ISM Manufacturing PMI hit 55.6 in July, its best reading since May 2022, and ISM Services remained steady at 54.1.5
Earnings
By the end of August, almost all S&P 500 companies had reported second-quarter earnings. As the reporting season progressed, the index’s earnings growth rate increased from 23% at the end of June to 52% by the end of August, marking the strongest quarterly earnings growth since the second quarter of 2021.6 Revenue growth also accelerated to 15.5%, the highest since the fourth quarter of 2021.6 S&P 500 net profit margins reached a record 17.0%, the highest reading since FactSet began tracking the metric in 2009. Looking ahead, analysts expect full-year 2026 S&P 500 earnings to grow 31%, followed by a further 14% increase in 2027.6
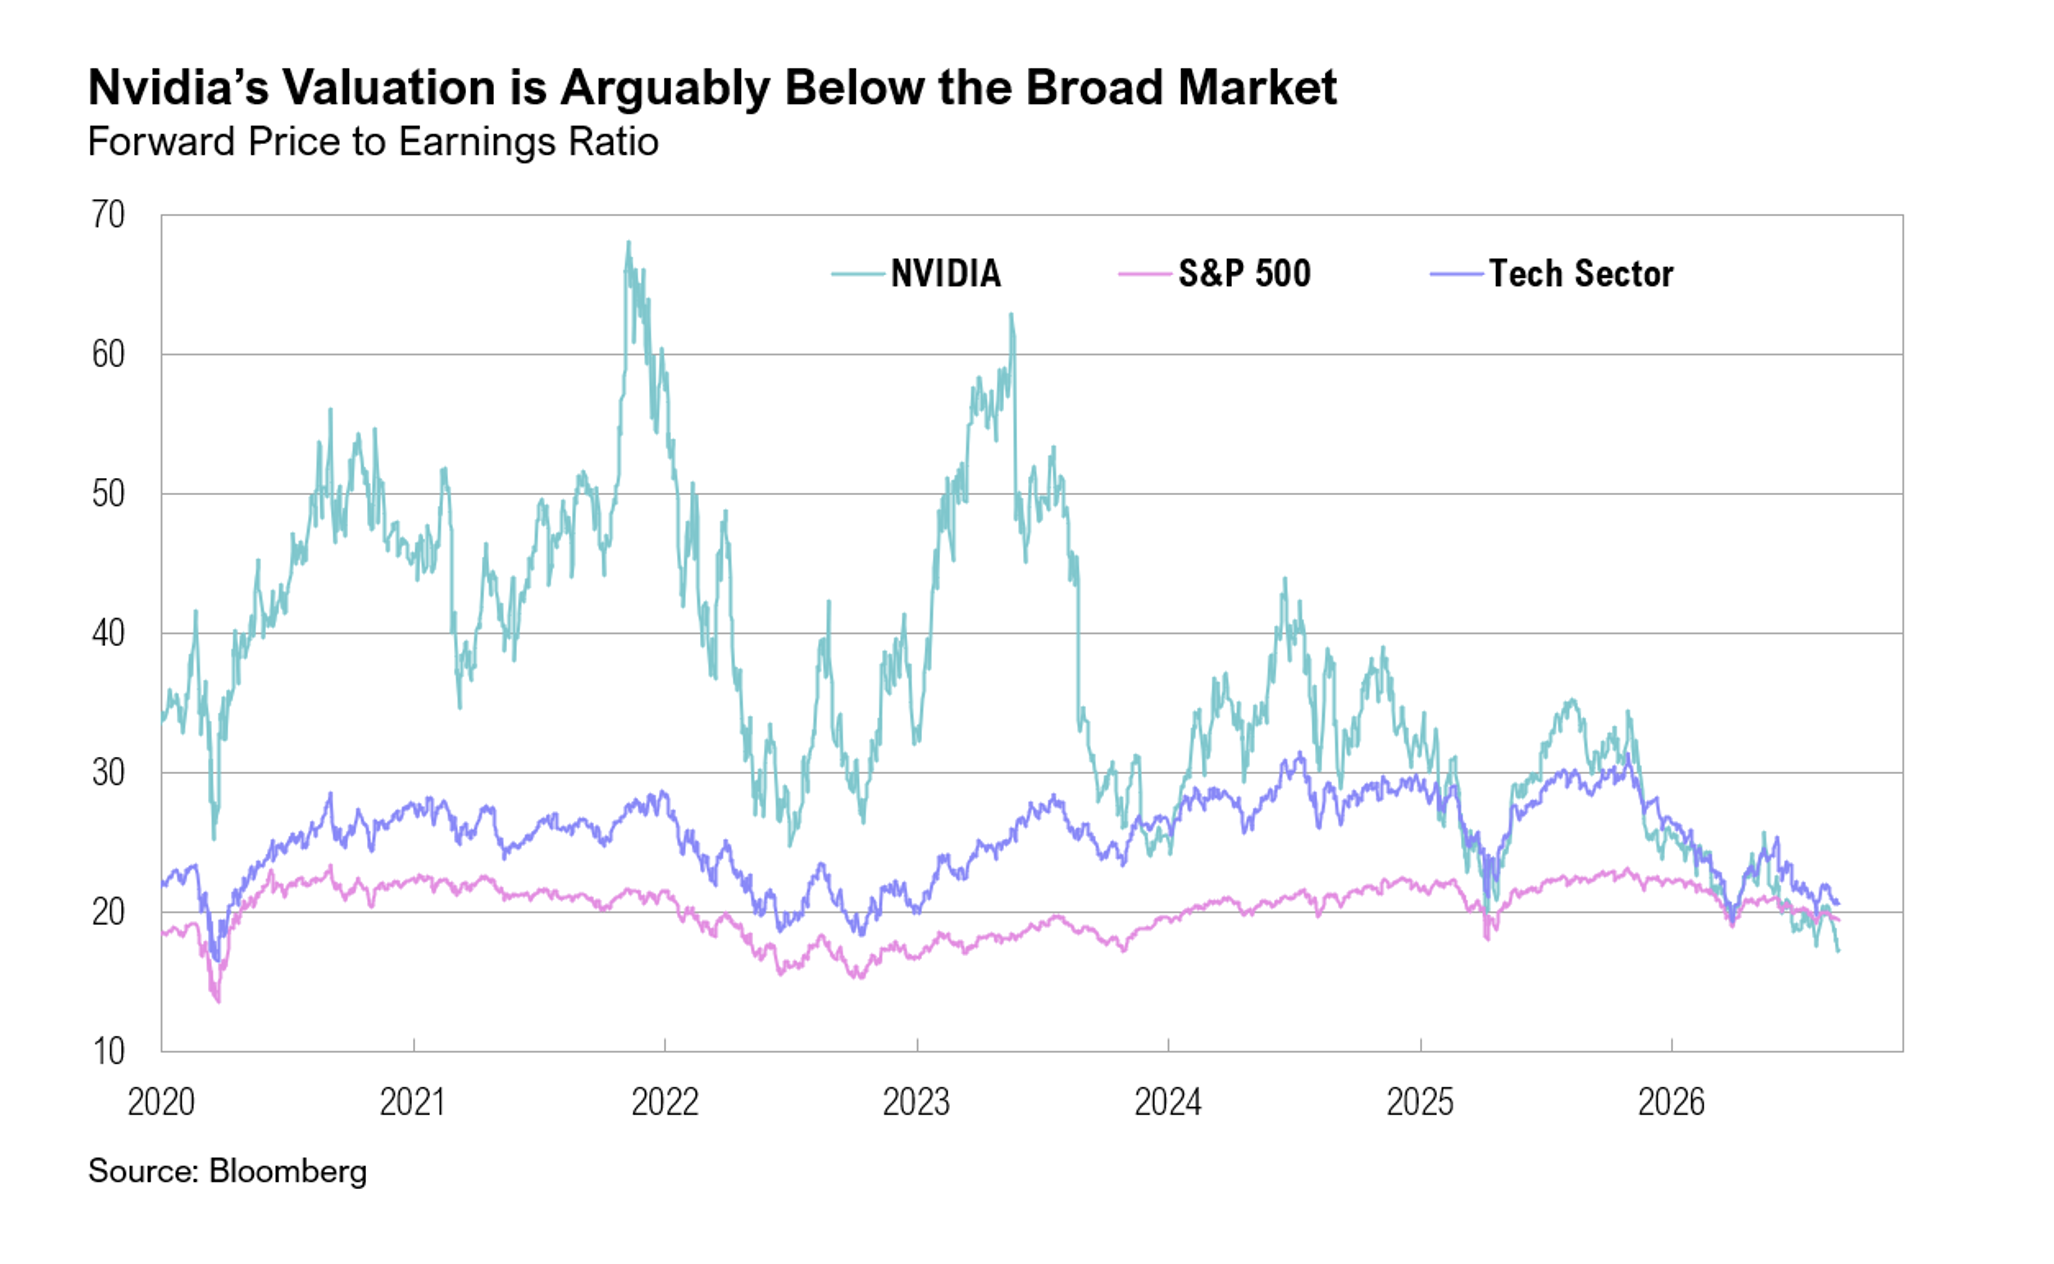
NVIDIA reported record quarterly revenue of $96 billion, up 106% year over year, and data center revenue was up 117%.7 The results beat consensus on both the top and bottom lines, and management raised the outlook for the next fiscal year to roughly 70% revenue growth. Management indicated that unconstrained demand would run meaningfully higher than the roughly 70% growth figure implied and that the 70% instead reflects what NVIDIA can confidently supply, with supply remaining the bottleneck.7 Asked directly what growth would look like unconstrained, CEO Jensen Huang responded:
“The unconstrained would be a lot higher. We grew 100% year-over-year this year. The unconstrained is significant. And so, we’re just going to have to work hard to get more capacity.”7
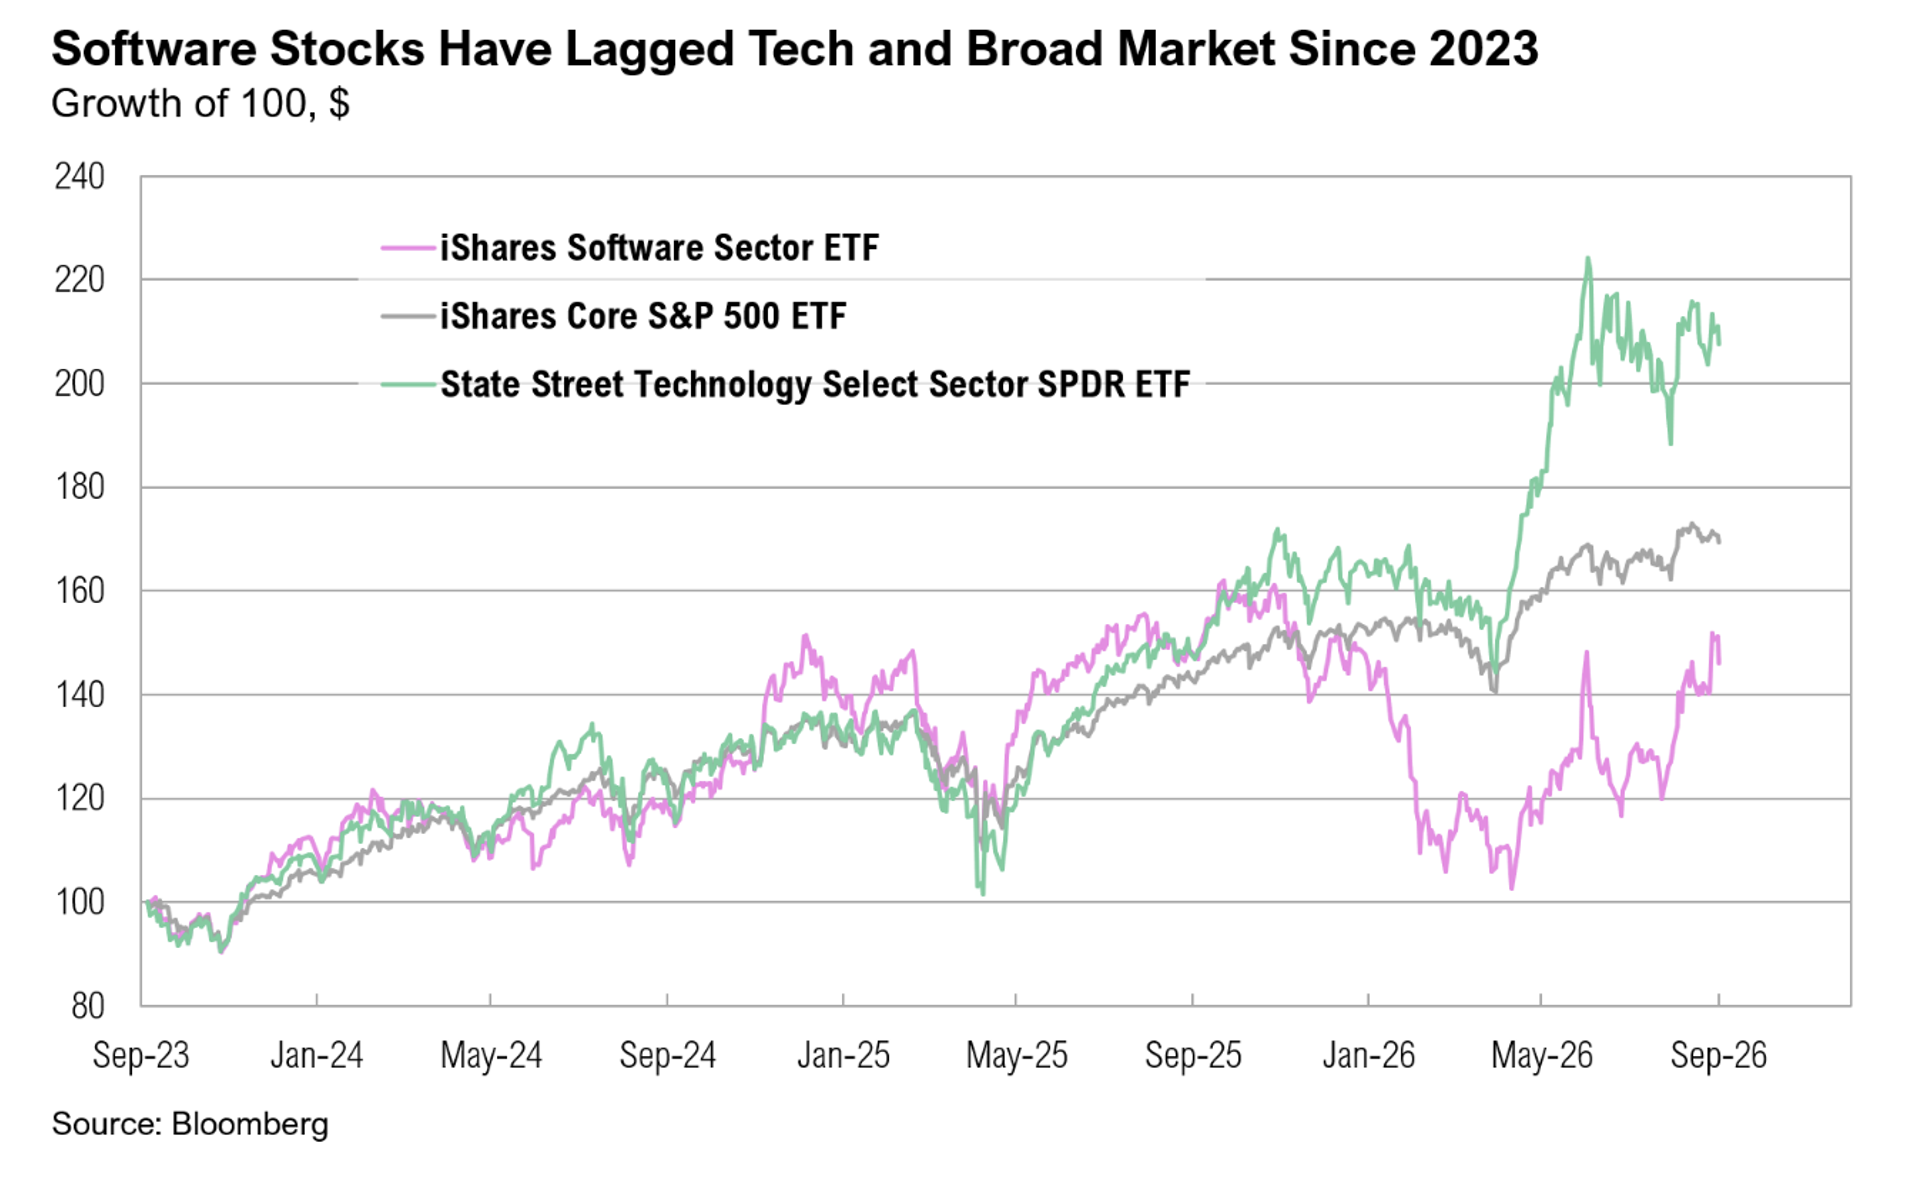
Software stocks continued their sharp climb from the “SaaSpocalypse” selloff earlier this year, which took the group down more than 35% before it bottomed in April. Since then, software has rebounded more than 45%, returning to positive territory year to date, although much of that gain has simply recovered ground lost earlier in the year. The rebound itself has been lopsided. Cybersecurity rose 84% from its lows, compared with 46% for the iShares Expanded Tech-Software ETF, 30% for the Technology Select Sector SPDR Fund, and 13% for the S&P 500. More recently, the rally broadened beyond cybersecurity. Some software companies benefitted from AI adoption rather than facing the disruption initially feared.8 On August 27, Salesforce rose 23% after stronger-than-expected second-quarter results and improved guidance, underpinned by accelerating AI-related demand, and Agentforce annual recurring revenue exceeded $1.5 billion, up more than 240% year-over-year.8
Jackson Hole
Jackson Hole has become one of the Fed’s most important venues for signaling changes in policy. Fed chairs have repeatedly used the symposium to frame major shifts before they are reflected in formal Federal Open Market Committee decisions.9 Former Fed Chair Ben Bernanke used the platform in 2010 to lay the groundwork for a second round of quantitative easing and returned in 2012 to signal a third round of easing later that year. In 2022, Fed Chair Jerome Powell used Jackson Hole to deliver a blunt warning that restoring price stability would bring “pain” to households and businesses, prompting a sharp drop across major equity indices as markets recalibrated to a more aggressive rate-hike path.10
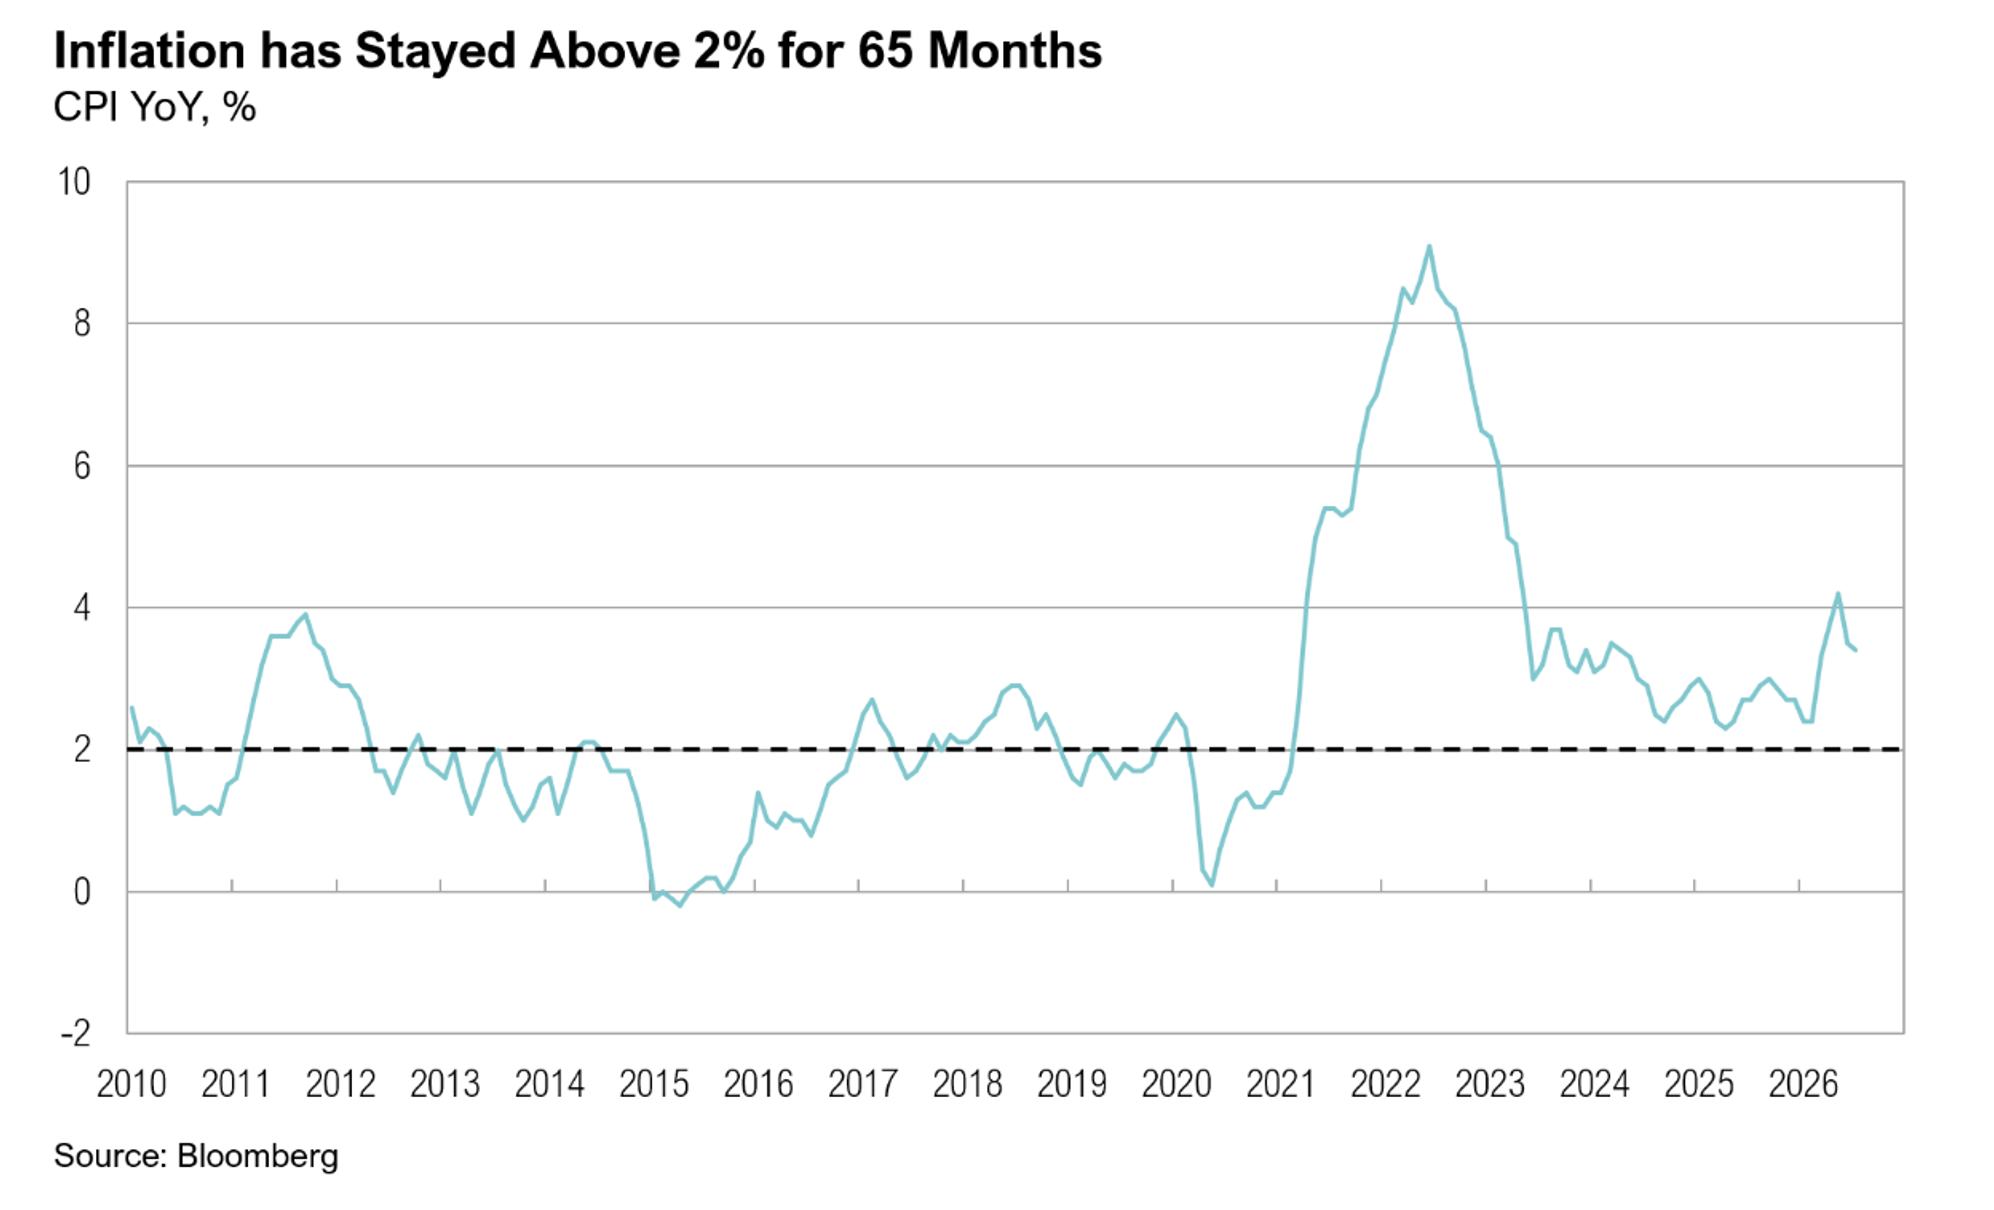
Two years before that, Powell used Jackson Hole to introduce a flexible average inflation targeting framework, intended to allow inflation to run modestly above 2% following a sustained period of undershoot and to give policymakers more room to support the labor market.11 Inflation ultimately ran far beyond that intended modest overshoot, with CPI peaking at 9.1% in June 2022. The 2020 framework shift remains part of this year’s backdrop, as inflation has now remained above the Fed’s 2% target for 65 consecutive months. 12
This year’s theme, “Financial Innovation: Implications for Payments and Policy,” gave Kevin Warsh his first high-profile opportunity as Fed Chair to lay out his framework. He focused on AI, forward guidance, the principles guiding monetary policy, and his assessment of the economy today. Warsh also highlighted five Fed task forces reviewing areas including communications, balance-sheet policy, inflation frameworks, and the implications of emerging technologies for productivity and employment. Warsh noted that their recommendations will come later and will not affect current policy decisions.12
Consistent with his public comments since his January nomination, Warsh reiterated his opposition to forward guidance, arguing that explicit signaling can create a feedback loop between the Fed and markets that leaves policymakers less prepared when conditions change:
“The economic literature has long described the distorting effects: a hall-of-mirrors problem. If markets rely materially on the Fed’s guidance and the Fed relies on market prices, we are all more likely to be blinded to new developments … more likely to be caught unprepared for a turn of events … and more likely to commit errors in policymaking.”12
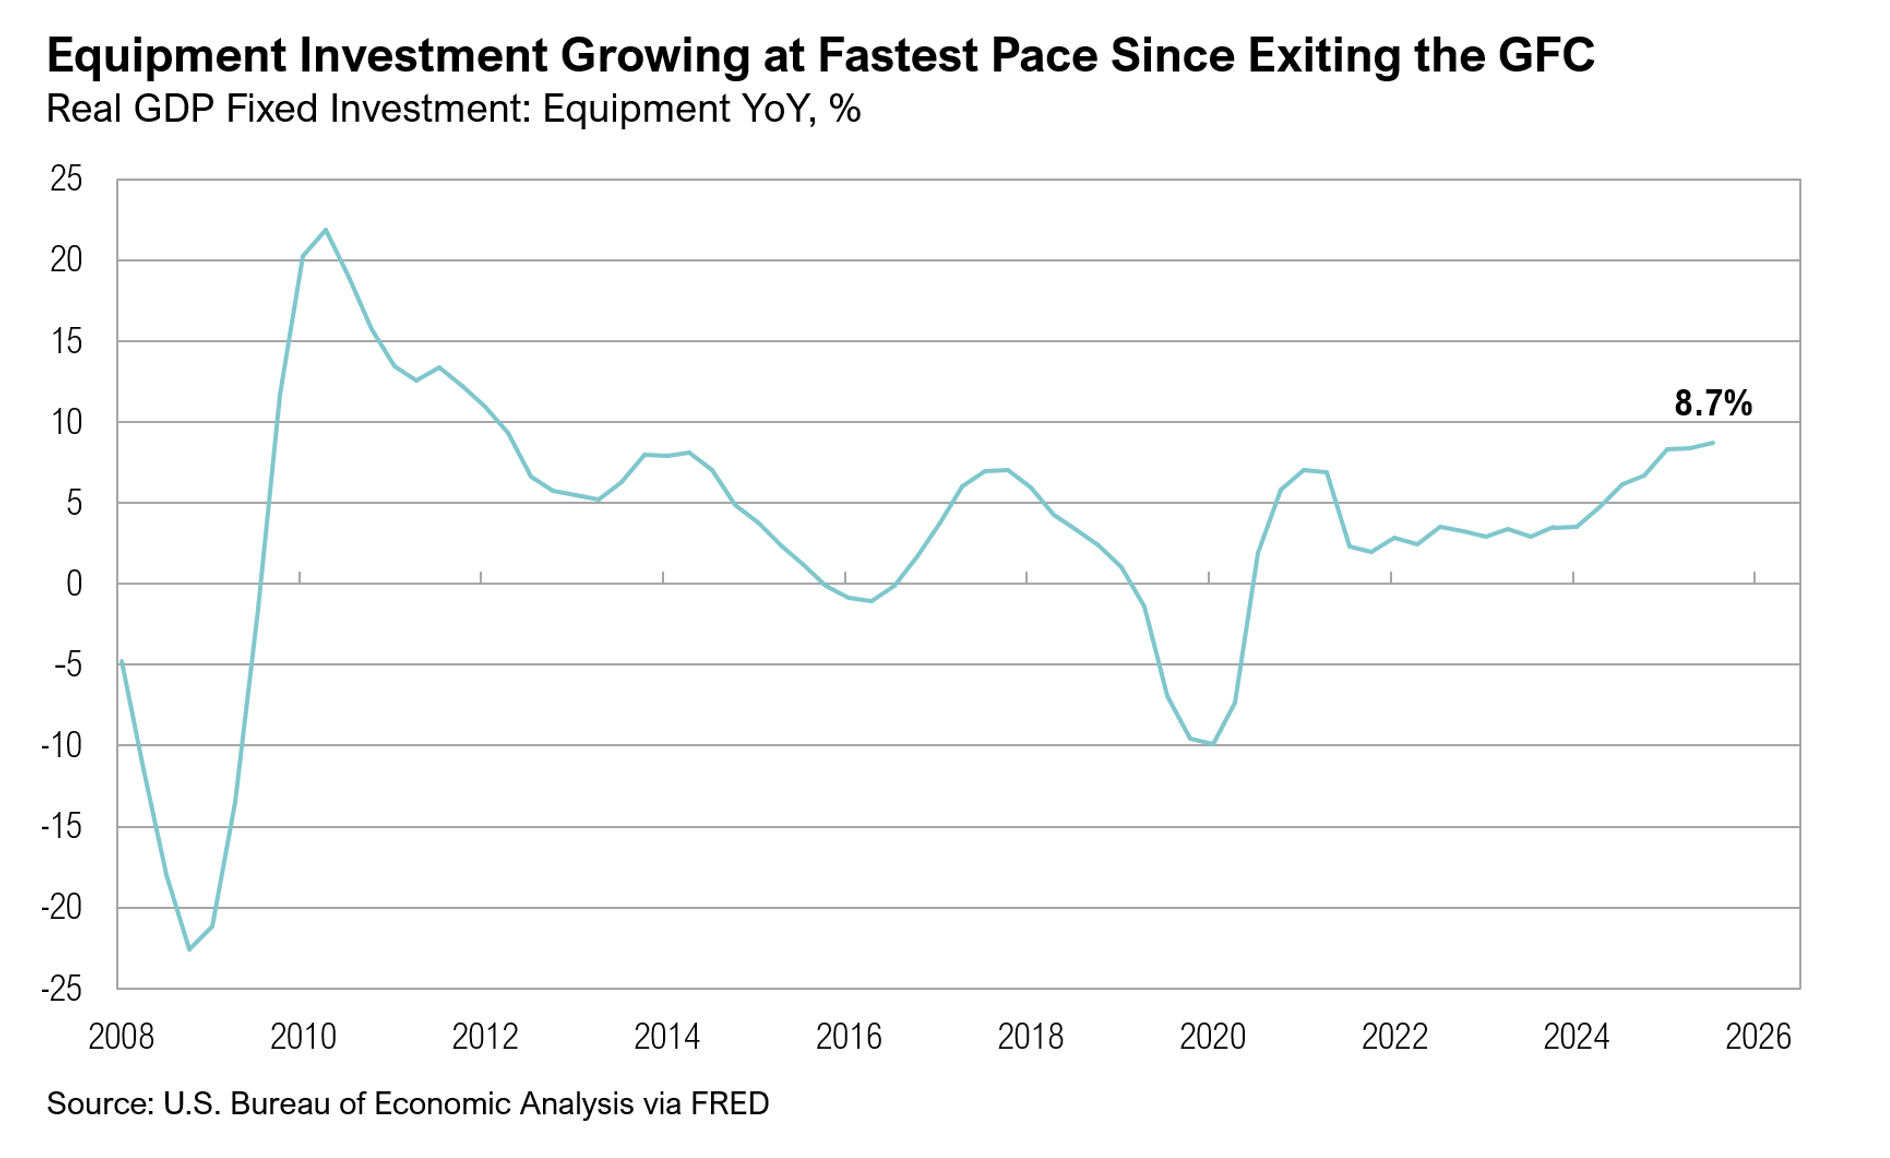
Warsh characterized current economic conditions as healthy, citing low unemployment, solid private-sector demand, and accelerating business investment, including AI-related capital spending. On inflation, however, he acknowledged that progress remains incomplete. Roughly 54% of goods and services in the Fed’s preferred PCE measure have risen more than 3% over the past year, down from a post-pandemic peak of roughly 77% but still well above the 32% average that prevailed during the two decades before the pandemic.12
Warsh also reiterated his skepticism toward quantitative easing as a routine policy tool, arguing that short-term interest rates should remain the Fed’s primary instrument and unconventional policies should generally be reserved for genuine crises. That preference is already visible in Fed operations. Reserve-management purchases, the routine Treasury bill buying used to maintain ample bank reserves, fell to zero in mid-August. The program began at up to $40 billion per month in December 2025 before declining to $25 billion in April, $10 billion by mid-2026, and ultimately zero as reserve levels normalized.13,14
Markets responded quickly. September rate-hike probabilities, which had fallen sharply through July on softer inflation and labor data, moved back to 62% following the speech, while Treasury yields rose across the curve and continued higher into September.15
Markets
The S&P 500 Index gained 2.7% in August, outperforming the MSCI EAFE Index, which rose 2.0%. U.S. intermediate-term bonds gained 0.4% but remained negative year to date.
Long-dated Treasuries remained under pressure. The 30-year yield reached its highest level since 2007 on August 17, a move that partly reflected higher real yields and that Warsh has attributed to underlying economic strength and reduced reliance on forward guidance.16 Treasury Secretary Scott Bessent has also pointed to increased hyperscaler debt issuance as a source of pressure on longer-term yields.17 The Treasury subsequently announced that it would at least double the size of its 10- to 30-year buyback operations, from $2 billion to at least $4 billion per operation beginning September 9. Treasury characterized the change as an expansion of an existing liquidity-management program rather than a new initiative.18
From the buyback announcement through month end, gold gained 2% and Bitcoin rose 22%. The 10-year Treasury yield increased 5 basis points to 4.75%, while the 30-year yield declined 4 basis points to 5.24%.
Looking Forward
Longer-term interest rates are particularly important to economic activity and market valuations, influencing borrowing costs across the economy and the discount rates applied to financial assets. While short-term rates remain closely tied to monetary policy, longer-term rates must also absorb Treasury supply, fiscal pressures, and nominal GDP growth that has accelerated to levels last seen in the early 2000s, outside of the COVID-19 recovery.
We believe the Fed and Treasury are increasingly coordinating their respective policy tools in response to these pressures. Warsh has argued for less reliance on the Fed’s balance sheet and a return to short-term interest rates as the primary tool of monetary policy, while Treasury has expanded its long-end buyback program. The buybacks remain tiny relative to quantitative easing, so we view them less as a market-moving force and more as a signal that Treasury is willing to use its debt-management tools more actively.
Warsh’s broader argument that unconventional policies such as quantitative easing should be reserved for genuine crises represents a meaningful break from some of the policy constructs that followed Jackson Hole 2020 and, in our view, contributed to the subsequent inflationary episode. AI adds another wrinkle. Warsh noted that AI could become a new factor of production with implications for both the economy and monetary policy. The buildout is already supporting capital spending and credit demand, but the productivity payoff may matter more. If AI allows the economy to grow faster without generating comparable inflation, the Fed could ultimately have more room to accommodate stronger growth. If that payoff is slower to emerge while investment and nominal growth remain strong, pressure on longer-term rates could persist.
The combination of a changing Fed framework, less forward guidance, pressure at the long end of the curve, and uncertainty around AI-driven productivity leaves a wide range of possible outcomes for the remainder of 2026 and into 2027. We remain focused on assets with attractive risk/reward potential across those outcomes, while generally favoring an allocation geared toward higher nominal growth and recognizing that sustained productivity gains from AI could prove supportive across markets. At the end of the day, investors can debate what the Fed and Treasury should do, but markets will be driven by what they actually do.
Performance Disclosures
All market pricing and performance data from Bloomberg, unless otherwise cited. Asset class and sector performance are gross of fees unless otherwise indicated.
Citations
- BEA: U.S. Bureau of Economic Analysis (BEA)
- Bureau of Labor Statistics: Current Employment Statistics – CES (National) : U.S. Bureau of Labor Statistics
- U.S. Census Bureau: NRC – Data
- The Conference Board: US Consumer Confidence
- ISM: ISM® PMI® Reports
- FactSet: FactSet Earnings Insight
- NVIDIA: NVIDIA Corporation – NVIDIA 2nd Quarter FY27 Financial Results
- Salesforce: Q2 FY27 Quarterly Investor Deck
- Kansas City Fed: Jackson Hole Economic Policy Symposium Through the Years – Federal Reserve Bank of Kansas City
- CNBC: Powell comments fuel 1,000-point market rout Friday as stocks slide for a second week
- Federal Reserve: Speech by Chair Powell on new economic challenges and the Fed’s monetary policy review – Federal Reserve Board
- Federal Reserve: Keynote remarks by Chairman Warsh at the 2026 Jackson Hole Economic Policy Symposium – Federal Reserve Board
- New York Fed: The Implementation of Reserve Management Purchases to Maintain Ample Reserves
- New York Fed: Treasury Securities Operational Details – FEDERAL RESERVE BANK of NEW YORK
- CME Group: FedWatch – CME Group
- Federal Reserve: Transcript of Chairman Warsh’s Press Conference — July 29, 2026
- CNBC: CNBC Exclusive: Transcript: U.S. Treasury Secretary Scott Bessent Speaks with CNBC’s Sara Eisen on “Squawk on the Street” Today
- U.S. Department of Treasury: Treasury Announces Increased Sizes of Nominal Long-End Liquidity Support Buybacks Beginning September 9 | U.S. Department of the Treasury
Index Definitions
The S&P 500 Index is widely regarded as the best single gauge of the United States equity market. It includes 500 leading companies in leading industries of the U.S. economy. The S&P 500 focuses on the large cap segment of the market and covers approximately 75% of U.S. equities.
The Bloomberg Barclays U.S. Aggregate Index represents securities that are SEC-registered, taxable, and dollar denominated. The index covers the U.S. investment grade fixed rate bond market, with index components for government and corporate securities, mortgage pass-through securities, and asset-backed securities. Duration is roughly 5 years.
The Bloomberg U.S. Corporate High Yield Bond Index measures the USD-denominated, high yield, fixed-rate corporate bond market. Securities are classified as high yield if the middle rating of Moody’s, Fitch and S&P is Ba1/BB+/BB+ or below. Bonds from issuers with an emerging markets country of risk, based on the indices’ EM country definition, are excluded.
The Bloomberg GlobalAgg Index is a flagship measure of global investment grade debt from a multitude local currency markets. This multi-currency benchmark includes treasury, government-related, corporate and securitized fixed-rate bonds from both developed and emerging markets issuers.
The Russell 2000® Index measures the performance of the small-cap segment of the US equity universe. It includes approximately 2000 of the smallest US equity securities in the Russell 3000 Index based on a combination of market capitalization and current index membership. The Russell 2000 Index represents approximately 10% of the total market capitalization of the Russell 3000 Index. Because the Russell 2000 serves as a proxy for lower quality, small cap stocks, it provides an appropriate benchmark for RMB Special Situations.
The U.S. Dollar Index is used to measure the value of the dollar against a basket of six foreign currencies: the euro, Swiss franc, Japanese yen, Canadian dollar, British pound, and Swedish krona.
MSCI U.S. REIT Index is a free float-adjusted market capitalization weighted index that is comprised of equity Real Estate Investment Trusts (REITs). The index is based on the MSCI USA Investable Market Index (IMI), its parent index, which captures the large, mid and small cap segments of the USA market. With 150 constituents, it represents about 99% of the US REIT universe and securities are classified under the Equity REITs Industry (under the Real Estate Sector) according to the Global Industry Classification Standard (GICS®), have core real estate exposure (i.e., only selected Specialized REITs are eligible) and carry REIT tax status.
The MSCI China Index captures large and mid cap representation across China A shares, H shares, B shares, Red chips, P chips and foreign listings (e.g. ADRs). The index covers about 85% of this China equity universe. Currently, the index includes Large Cap A and Mid Cap A shares represented at 20% of their free float adjusted market capitalization.
The MSCI India Index is designed to measure the performance of the large and mid cap segments of the Indian market. With 165 constituents, the index covers approximately 85% of the Indian equity universe.
The MSCI EAFE Index is an equity index which captures large and mid cap representation across Developed Markets countries around the world, excluding the US and Canada. The index covers approximately 85% of the free float-adjusted market capitalization in each country.
The MSCI Emerging Markets Index captures large and mid cap representation across 24 Emerging Markets (EM) countries*. With 1,178 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in each country.
The MSCI ACWI Index captures large and mid cap representation across Developed Markets (DM) and Emerging Markets (EM) countries. The index covers approximately 85% of the global investable equity opportunity set.
Disclaimers
*Source: MSCI.MSCI makes no express or implied warranties or representations and shall have no liability whatsoever with respect to any MSCI data contained herein. The MSCI data may not be further redistributed or used as a basis for other indexes or any securities or financial products. This report is not approved, endorsed, reviewed or produced by MSCI. None of the MSCI data is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such.
The opinions and analyses expressed in this newsletter are based on Curi Capital, LLC’s (“Curi Capital”) research and professional experience are expressed as of the date of our mailing of this newsletter. Certain information expressed represents an assessment at a specific point in time and is not intended to be a forecast or guarantee of future results, nor is it intended to speak to any future time periods. Curi Capital makes no warranty or representation, express or implied, nor does Curi Capital accept any liability, with respect to the information and data set forth herein, and Curi Capital specifically disclaims any duty to update any of the information and data contained in this newsletter. The information and data in this newsletter does not constitute legal, tax, accounting, investment or other professional advice. Returns are presented net of fees. An investment cannot be made directly in an index. The index data assumes reinvestment of all income and does not bear fees, taxes, or transaction costs. The investment strategy and types of securities held by the comparison index may be substantially different from the investment strategy and types of securities held by your account.